
Key Takeaways:
- Tungsten concentrate prices tripled from $750-$850 to $2,500-$2,800 per metric tonne unit in 2026, driven by a collision of Chinese export limits and new US sourcing rules.
- China restricted tungsten exports to 15 authorized firms through 2027, while the United States tightened defense procurement rules effective January 1, 2027.
- North American explorers and processors, including GoldHaven Resources and Almonty Industries, are racing to build non-Chinese supply as new mines take five to ten years to reach production.
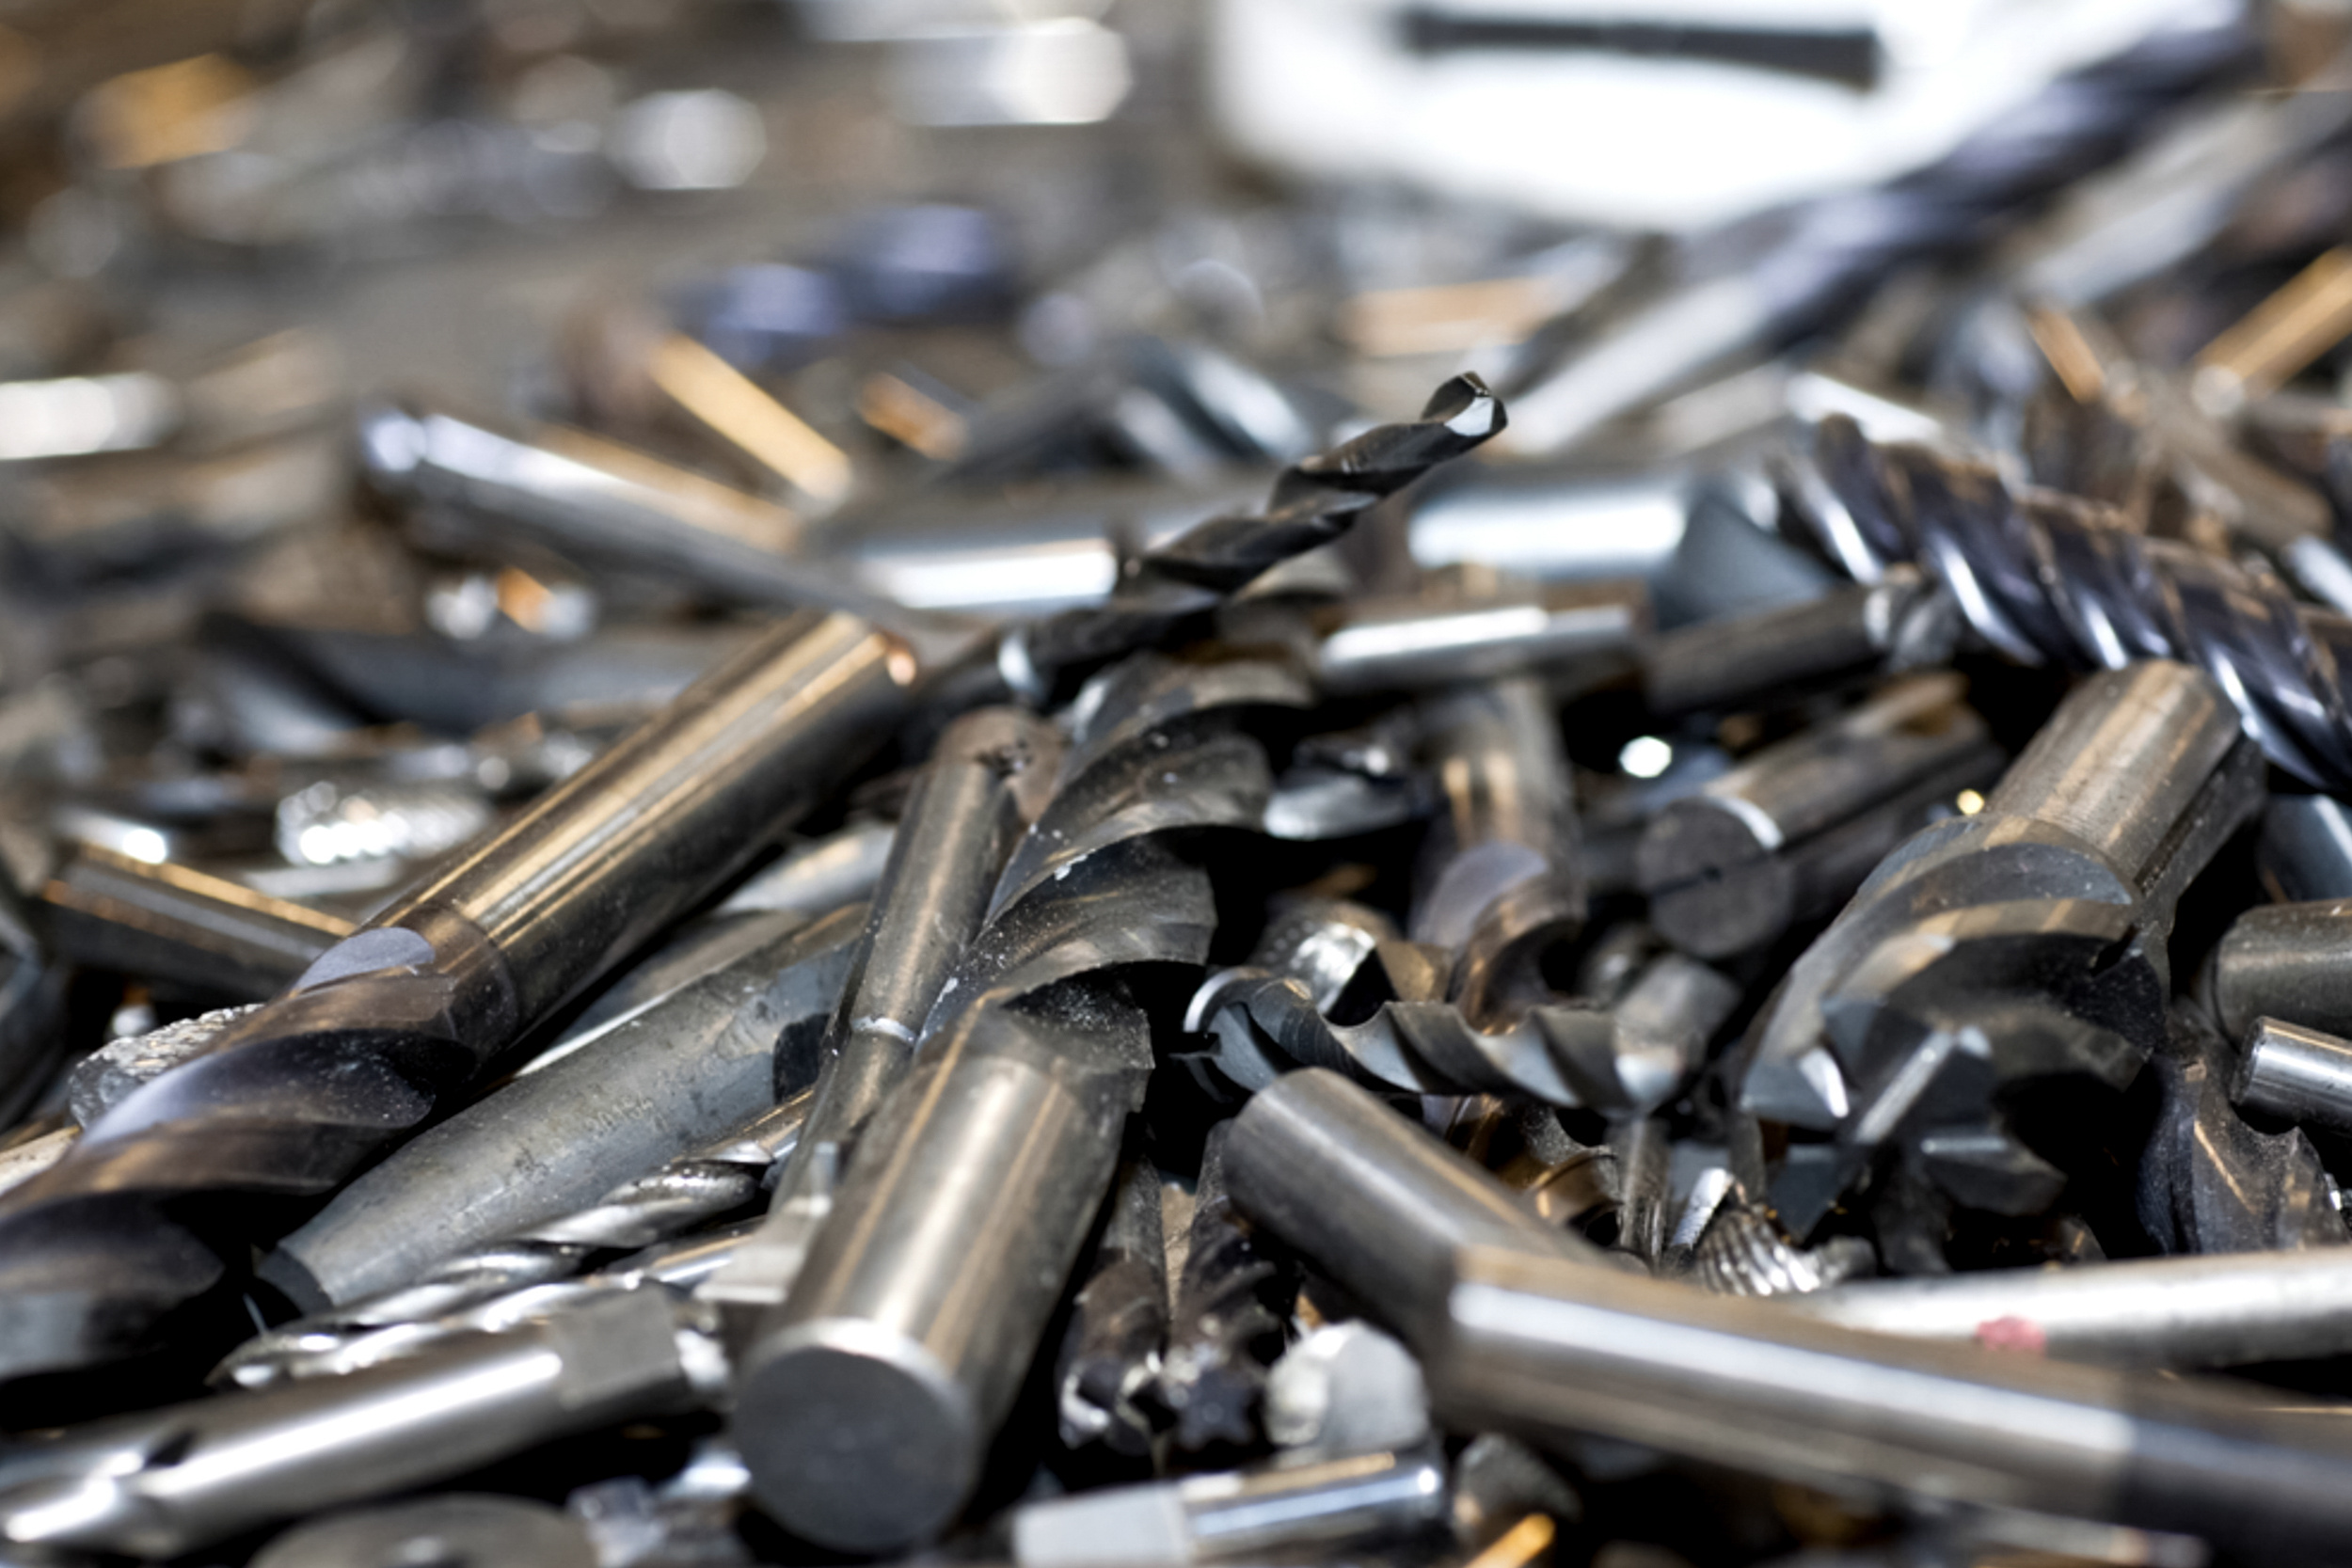
Tungsten rarely makes headlines. The metal’s exceptional hardness and heat resistance make it vital for cutting tools, drilling equipment, and defense applications, yet it has stayed largely invisible to anyone outside heavy industry. That changed in 2026, when concentrate prices roughly tripled in just a few months.
The jump stems from two governments pulling in opposite directions at the same time, and the resulting squeeze reaches far beyond the mining sector. Toolmakers, defense contractors, and recyclers are all adjusting to a market that looks nothing like it did a year ago.
Why Does Tungsten Matter Now?
China mines roughly 79% of the world’s tungsten supply, leaving the rest of the world with little room to maneuver when Beijing tightens exports. The United States hasn’t produced tungsten from a domestic mine since 2015 and depends entirely on imports and recycled material to meet demand. That means a single policy shift in China can quickly turn into a global price shock.
What Triggered the 2026 Price Spike?
China’s Ministry of Commerce embedded tungsten in its dual-use export catalog in December 2025, limiting exports to a whitelist of just 15 authorized firms through 2027. Unlike a negotiable quota, that framework is difficult to contest or unwind.
Washington answered with its own measures. A temporary rule effective August 27, 2026, requires US sellers to direct 100% of monthly tungsten scrap sales to domestic buyers. Then comes the bigger shift: starting January 1, 2027, US defense procurement rules extend back to the mine or ore stage and explicitly cover recycled material, closing a loophole that once let processed material reset its country of origin.
Who Is Racing to Fill the Supply Gap?
North American companies are moving to capture the opportunity. GoldHaven Resources secured permits for 93 drill pads across seven work zones at its Magno Project in British Columbia, with 2026 drilling focused on tungsten-bearing skarn at its Kuhn target. Almonty Industries completed certification for its Sangdong processing plant in South Korea, clearing the way for commercial production. Meanwhile, reports point to U.S. federal capital flowing toward domestic tungsten manufacturing in states including Nevada, Maine, Michigan, and Ohio.
New tungsten projects typically take five to ten years to reach commercial production, meaning supply can’t catch up with policy-driven demand overnight. That lag supports the case that elevated prices are not temporary.
The companies that convert permits and announcements into traceable, reliable supply will matter most as the January 2027 deadline approaches. For now, the divide between policy and production remains wide, and closing it will take years, not quarters.
(Note: AI assisted in summarizing the key points for this story.)