
Key Takeaways:
- European steel production fell to a record low of 125.8 million tonnes in 2025 while imports climbed to roughly 30% of consumption, according to EUROFER, leaving mills running near 70% capacity and short of the margins needed to fund green steel investment.
- The switch to electric arc furnaces and hydrogen-based direct reduced iron is expensive: European industrial electricity runs above 100 euros per megawatt-hour versus 30 to 50 euros in China and the United States, and clean hydrogen costs 5 to 8 euros per kilogram.
- Brussels is responding with the Carbon Border Adjustment Mechanism and a new steel trade regime that cuts tariff-free import quotas by about 47% and applies a 50% duty above them, both arriving in 2026.
European steelmakers are being asked to clean up fast while demand stays soft, energy bills stay high, and cheaper imports keep arriving. Steel underpins much of modern infrastructure so the decisions made now will shape Europe’s industrial base for decades.
The core problem is that mills need to spend heavily on cleaner production, yet many aren’t earning enough today to make those bets easily. EU crude steel output dropped 2.9% in 2025 to its lowest level on record, according to EUROFER, even as consumption grew 4.4%. The reason for that disconnect is that recovering demand is increasingly met by imports, which reached about 30% of the market.
Why Does Green Steel Cost So Much?
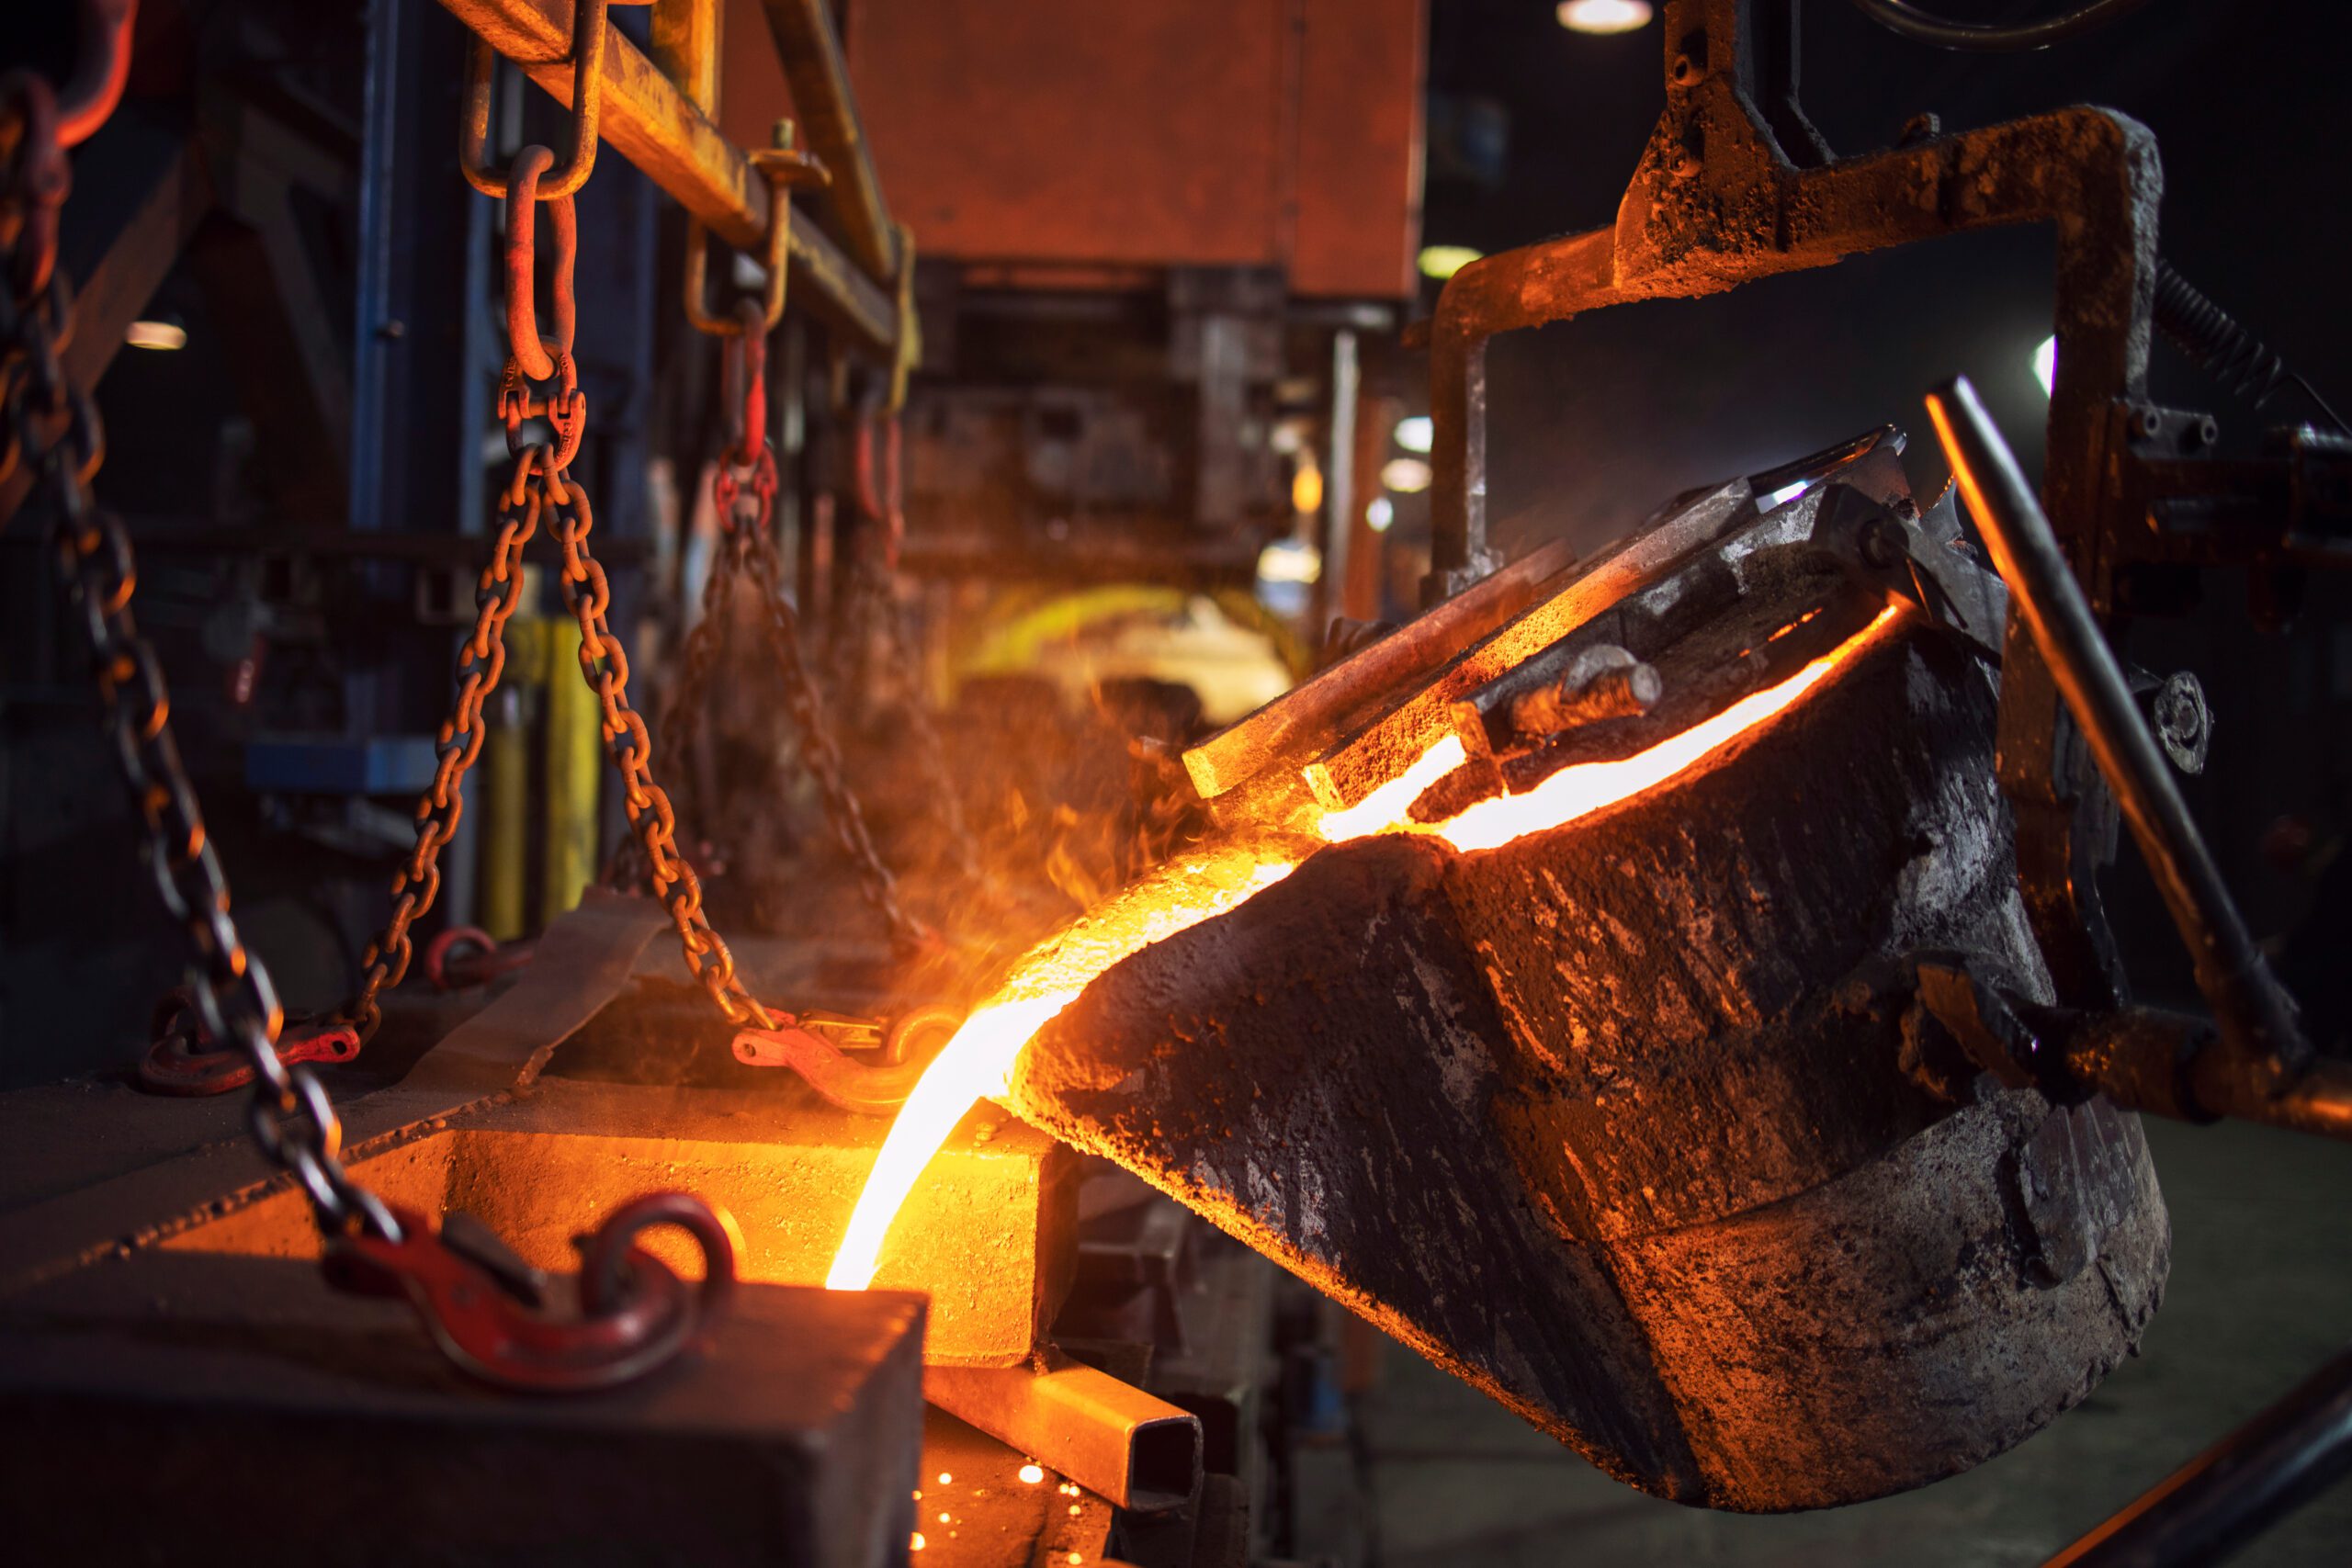
Swapping a blast furnace for electric arc technology isn’t a simple trade. Electric arc furnaces cut direct emissions and run mostly on scrap, but scrap quality and supply vary, which limits how far mills can lean on them. Hydrogen-fueled direct reduced iron offers another route, but the economics remain punishing.
Energy is the pressure point. European industrial users often pay more than 100 euros per megawatt-hour, compared with 30 to 50 euros in the United States and China. Green hydrogen adds 5 to 8 euros per kilogram, which can drive up iron costs.
The market has taken note. ArcelorMittal scrapped plans for hydrogen direct reduced iron modules in Germany despite government funding, thyssenkrupp put a green steel tender on hold, and Salzgitter delayed a decision on its SALCOS project. Subsidies help with the first bill, but they don’t guarantee affordable power or buyers willing to pay a premium.
Can Europe Compete Against Lower-Cost Producers?
Global overcapacity adds to the issue. The OECD projects world excess capacity climbing toward 721 million tonnes by 2027, much of it from Asian producers operating under cheaper energy and lighter regulation. Steel is a globally traded commodity, so European mills can’t simply pass rising costs to buyers when imports sit on the shelf.
EU imports rose 14% in 2025, and capacity utilization has remained around 70%, well below the roughly 80% needed to fund modernization.
Trade policy is the EU’s first move. The Carbon Border Adjustment Mechanism becomes fully operational in 2026, adding carbon costs to high-emission imports. Chinese slab, for example, faces roughly 144 euros per tonne in charges.
A new trade regime, targeted for mid-2026, will cut tariff-free quotas by about 47% and impose a 50% duty on volumes above them. A “melt and pour” origin rule intends to track where steel is actually made, blocking relabeling and transhipment.
The Road Ahead
The European steel sector generates roughly 152 billion euros in gross value added, directly employs about 293,000 people, and supports more than 2.5 million jobs across manufacturing, according to EUROFER.
“Europe needs steel for mobility, construction, energy infrastructure, and defence, yet European steel production is under threat,” said Axel Eggert, EUROFER’s director general.
The most convincing route combines realistic decarbonization timelines, cheaper clean energy, targeted trade protection, and serious investment in skills. Europe can still turn green steel into a strength. It just needs a market that rewards the effort, or the mills may grow cleaner on paper while production quietly moves elsewhere.
(Note: AI assisted in summarizing the key points for this story.)